
An Employer Identification Number (EIN) helps identify the organisation behind a record. For grant research, use it to keep the applicant, funder and any other organisation being researched distinct. Status verification and funding fit are separate questions.
Start by checking the available status evidence, then review the particular funder’s current eligibility rules. This guide shows how to use an EIN and dated tax records without treating either as a guarantee that an application will qualify.
TL;DR: An EIN identifies an organisation; it does not establish tax exemption or eligibility for a particular grant. Check the relevant IRS records and any missing-result exceptions, then use the funder’s EIN to locate its dated Form 990-PF. On the 2025 form, Part XIV separates grants paid from future commitments. Compare that history with current application guidance before deciding whether to apply.
The Technical Foundation: EIN vs. Tax-Exempt Status
Nonprofit EIN Verification & Funder Intelligence Guide
There is a fundamental misunderstanding that plagues many young nonprofits and even some seasoned organizations: the belief that possessing an EIN is proof of tax-exempt status. It is not. An EIN (Employer Identification Number) is simply a tax ID number issued by the IRS to identify a business entity. A for-profit hardware store has an EIN; a corporate law firm has an EIN. Having one does not make you a charity.
Section 501(c)(3) describes a federal tax-exempt category. An EIN letter alone does not establish that status. Publication 78 helps check eligibility to receive deductible contributions, but it is not a complete list of every eligible organisation and it does not establish eligibility for an individual grant.
The IRS TEOS dataset guide explains that some eligible organisations, including churches and subordinates in a group ruling, may not appear separately in Publication 78. Review the relevant determination or group-exemption documentation when the search does not resolve the question.
How to Verify Status Using IRS TEOS (and Better Alternatives)
Use IRS Tax Exempt Organization Search (TEOS) for the available exemption, filing and determination-letter records. Note the dataset and date checked.
To verify status manually:
- Navigate to the IRS TEOS page.
- Select “Search for Tax Exempt Organizations” and choose “Pub 78 Data” from the dropdown menu.
- Enter the EIN (preferred for accuracy) or the organization’s name.
- Review the result’s deductibility code and the IRS explanation for that code; check the legal name and EIN refer to the intended organisation.
A missing result is a reason to investigate, not an automatic ineligibility verdict. Check spelling, EIN, determination or group-exemption documentation and the dataset’s coverage. FundRobin’s free EIN lookup can help locate an organisation record; use the 501(c)(3) checker and current IRS information for the separate status question. The organisation you search may be a funder or another organisation you are researching.
FundRobin case-study evidence (September 2026): nine US case-study organisations used FundRobin’s free EIN lookup and 501(c)(3) checker to verify 41 partner, sub-grantee and fiscal-sponsor organisations in one quarter. Six of the 41 needed follow-up because public records showed a different legal name or an unconfirmed status; those cases were resolved by cross-checking the official IRS Tax Exempt Organization Search. This is evidence from that defined case-study cohort, not a sector-wide rate.
The “Defense-to-Offense” Strategy: Reverse-Engineering Grant Opportunities
Once you have mastered the defensive side (verifying your own compliance), it is time to pivot to offense. This is where the EIN transforms from a tax number into a competitive intelligence asset. By integrating strategic grant discovery into your workflow, you can identify funders that align perfectly with your mission.
Use a foundation’s current website and its historical tax returns together. Current guidance describes application rules; a dated return records past activity. Find the intended foundation’s EIN and compare the latest available filings through ProPublica Nonprofit Explorer or IRS TEOS.
Decoding Form 990-PF: Finding the “Grants Paid” List
Start with the return’s form type and tax year. The 2025 IRS Form 990-PF instructions place supplementary information in Part XIV. Older forms can use different numbering, so follow the heading on the return being read.
In the 2025 Form 990-PF, line 3a records grants paid during the year; line 3b records amounts approved for future payment. Review any attached continuation schedules and keep those two amounts separate. The Form 990 prospecting guide walks through the next checks.
Use the grants list to guide further research:
- Compare peers: Note recipients with similar activities or geography, then check whether the foundation’s current priorities still align.
- Compare grant sizes: Separate project types and one-off awards; use the range and median as context alongside your project budget and current funder limits.
- Check access: Repeated recipients prompt a closer look at current application rules; they do not by themselves prove that unsolicited applications are closed.
Financial Health Benchmarks: Assessing Funder Viability
Financial figures need context. A foundation’s distribution calculation and an applicant’s public-charity classification answer different questions; neither alone establishes a funder’s viability or an applicant’s suitability.
The 5% Payout Rule and Private Foundations
For private non-operating foundations, the minimum-distribution calculation begins with a minimum investment return generally based on 5% of relevant net investment assets. Read the 2025 IRS Form 990-PF instructions for adjustments, qualifying distributions and timing.
This is not a grant budget or a ceiling on one applicant’s request. Qualifying distributions can include reasonable charitable administrative costs, and carryovers and timing affect the calculation.
The Math:
- If a foundation has $1,000,000 in net investment assets.
- Five per cent of that illustrative figure is $50,000, before the relevant adjustments.
Do not decide an ask from this arithmetic alone. Compare actual grants, current funding limits, the project’s justified costs and whether applications are accepted.
Public Support Tests Depend on Classification
Public charity status can arise under different classifications. The applicable public-support rules depend on that classification; a single one-third rule does not apply to every public charity. Check the determination letter and relevant Schedule A instructions.
The IRS overview of public charities describes these different categories. If funding concentration raises a question, have the organisation’s finance adviser review the applicable test and reporting period.
For grant research: confirm the classification and evidence requested by the particular funder instead of treating a single ratio as proof of compliance.
The Silent Killer: Automatic Revocation and “Pending” Status
Nothing drains a Development Director’s morale faster than securing a verbal “yes” from a donor, only to have the check withheld because of a compliance flag. The two most common culprits are Automatic Revocation and “Pending” status.
Automatic revocation: failure to file required annual returns or notices for three consecutive years can trigger revocation. A historical listing does not prove that status is still revoked: check reinstatement dates, the latest determination letter and current IRS records. The IRS explanation covers the process and applicable exceptions.
Pending applications: a submitted exemption application is not an approval. Review current IRS application information and ask the relevant funder which evidence it requires before investing in a proposal.
State charitable-solicitation requirements are a separate question and vary by jurisdiction and activity. FundRobin’s US state charity registry search links to relevant registries; check the responsible state authority’s current requirements.
From Spreadsheet Hell to AI Discovery: Automating the Process
Keep a concise record of the source, tax year, verification date and unanswered questions for each prospect. That makes research reusable and helps another reviewer check the decision.
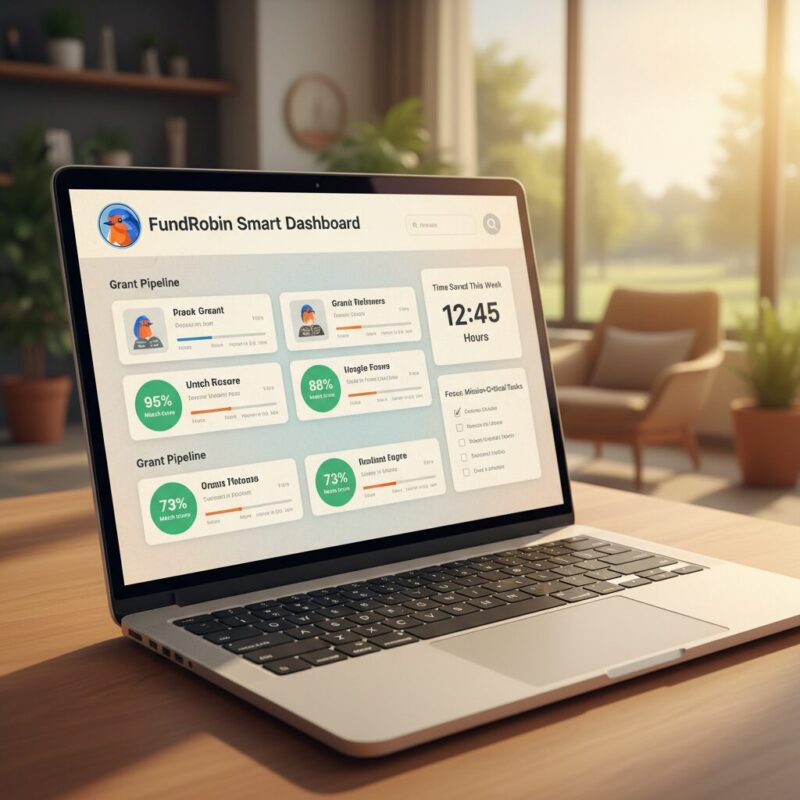
FundRobin can support organisation-specific discovery, opportunity-fit review and AI-assisted drafting. Its free lookup tools are separate from paid platform access. Verify IRS records and current funder requirements directly; FundRobin does not guarantee eligibility or funding.
The Automation Advantage:
- Smart Matching: compare organisation and opportunity context to prioritise fit, with rationale for human review.
- Reviewed context: retain useful organisation information and sources in Organisation Library and Organisation Brain; resolve missing or conflicting facts.
- Human decisions: treat a match signal as a prioritisation aid, not a funding probability or substitute for checking the return.
Using Validated Data to Draft Winning Proposals
The ultimate goal of this intelligence is not just finding the grant, but winning it. When you use accurate EIN data to reverse-engineer a funder’s history, you can tailor your narrative to align with their proven behavior.
Smart Proposal uses relevant organisation and opportunity context to help produce a structured first draft. People must review facts, budgets, eligibility and current application requirements before submission; measure any time saved within your own workflow.
Frequently Asked Questions
What is the difference between an EIN and 501(c)(3) tax-exempt status?
An EIN is a federal tax identifier, not proof of tax exemption or grant eligibility. Review current IRS records and relevant determination or group-exemption documentation; some eligible organisations do not appear separately in Publication 78.
How can I check if a nonprofit’s tax-exempt status has been revoked?
Check the IRS Automatic Revocation of Exemption List and any reinstatement date, then review the latest determination and current TEOS records. A historical revocation entry alone does not establish current revoked status.
What is the 5% payout rule for private foundations?
The minimum-distribution calculation for private non-operating foundations generally starts from 5% of relevant net investment assets, subject to adjustments and timing rules. It is not an available grants budget or a ceiling on an individual request.
Why is Form 990-PF important for grant research?
Form 990-PF records a private foundation’s historical activity. On the 2025 form, Part XIV line 3a lists grants paid and line 3b lists future commitments. Check the form year, attached schedules and current application rules before acting.
Are nonprofit tax returns (Form 990) public information?
Many nonprofit returns are publicly available through IRS TEOS and services such as ProPublica. Disclosure rules differ: Schedule B contributor information for Form 990 and 990-EZ is generally excluded from the TEOS returns dataset, while Form 990-PF Schedule B information is included.
How long does it take for the IRS to approve 501(c)(3) status?
Processing times depend on the application type and whether the IRS needs more information. Use the IRS page for current processing times and check TEOS for a determination; submitting an application does not establish approval. See current IRS processing information.
Key Takeaways:
- An EIN identifies an organisation; verify status and grant-specific eligibility separately.
- A missing Publication 78 result or historical revocation entry needs further checking.
- Read the dated Form 990-PF and distinguish paid grants from future commitments.
- Use current funder rules and project costs alongside historical giving; payout arithmetic does not set an ask.
- Keep sources reusable and review AI-assisted work before submission.
Conclusion
Use verification to resolve the status question and dated giving records to inform the funding question. Keep the source and date for each conclusion, and use the funder’s current rules before choosing the next action.
Funding-readiness checklist
- Confirm which organisation you are researching and which organisation would apply.
- Record the relevant status evidence, source and check date.
- Define a project, budget, geography and the funding needed.
- Compare current funder criteria with dated giving history, recording any unresolved questions.
If you are researching funding for an organisation you represent, you can apply for the guided Showcase Trial to evaluate FundRobin using your own grant workflow. The application is reviewed; organisation-profile preparation comes before activation. The 30-day period begins on FundRobin activation, and approved organisations do not need a card to begin. The free lookup remains available without a Showcase application.

Comments
One response to “Nonprofit EIN Verification & Intelligence: Uncover Hidden Funders”
[…] is the hundreds of hours wasted on manual grant searches and proposal drafting. By mastering the Nonprofit EIN Verification & Intelligence: Uncover Hidden Funders, you can accelerate your prospecting process […]